If you run a small business in Warrnambool or broader South West Victoria, you’ll know that cash flow problems rarely stay contained to one part of a business: a squeeze in one area, like a large annual insurance bill landing at the wrong time, can flow on to your ability to pay suppliers, staff, or your own bills on time.
The problem for South West Victoria businesses: one big bill, once a year
Most business premiums are due annually, and often several policies renew around the same time. Invoices for your public liability, building and contents, and commercial vehicle cover can all land in the same month, right when you might also be dealing with quarterly BAS, seasonal wage costs, or a slow trading period.
Paying it all upfront in one lump sum can mean drawing down cash reserves you’d rather keep for stock, wages, or opportunities that come up during the year. Some business owners respond by under-insuring just to make the number smaller…which creates a different kind of risk entirely.
The solution: insurance premium funding
This is where insurance premium funding comes in. Rather than paying your insurer one large amount upfront, a premium funder pays the insurer on your behalf, and you repay the funder in smaller, regular instalments over the year – they can be weekly, fortnightly, monthly or quarterly, depending on what suits your business.
You can also usually combine multiple policies across different insurers into a single funding arrangement, so instead of juggling separate due dates and separate payments to separate companies, you’re making one predictable payment each instalment.
What is it?
It’s important to note that premium funding is a form of borrowing. You’re not paying your premium in instalments for free: the funder charges interest on the amount financed, on top of what you’d otherwise pay for the policy itself.
That interest cost is, of course, worth weighing up. But for a lot of small businesses, it’s a reasonable trade-off for two reasons. First, the interest charged on premium funding is often modest relative to the value of not having to pull a large lump sum out of working capital all at once. Second, interest and any associated fees are generally tax-deductible as a business expense, which can soften the real cost further (obviously, discuss this with your accountant).
It’s also worth talking to your broker about structuring. Things like settlement timing and instalment frequency can be tailored to match when cash actually moves through your business, rather than defaulting to a generic monthly schedule.
A real example: Noodledoof Brewery & Distillery, Koroit
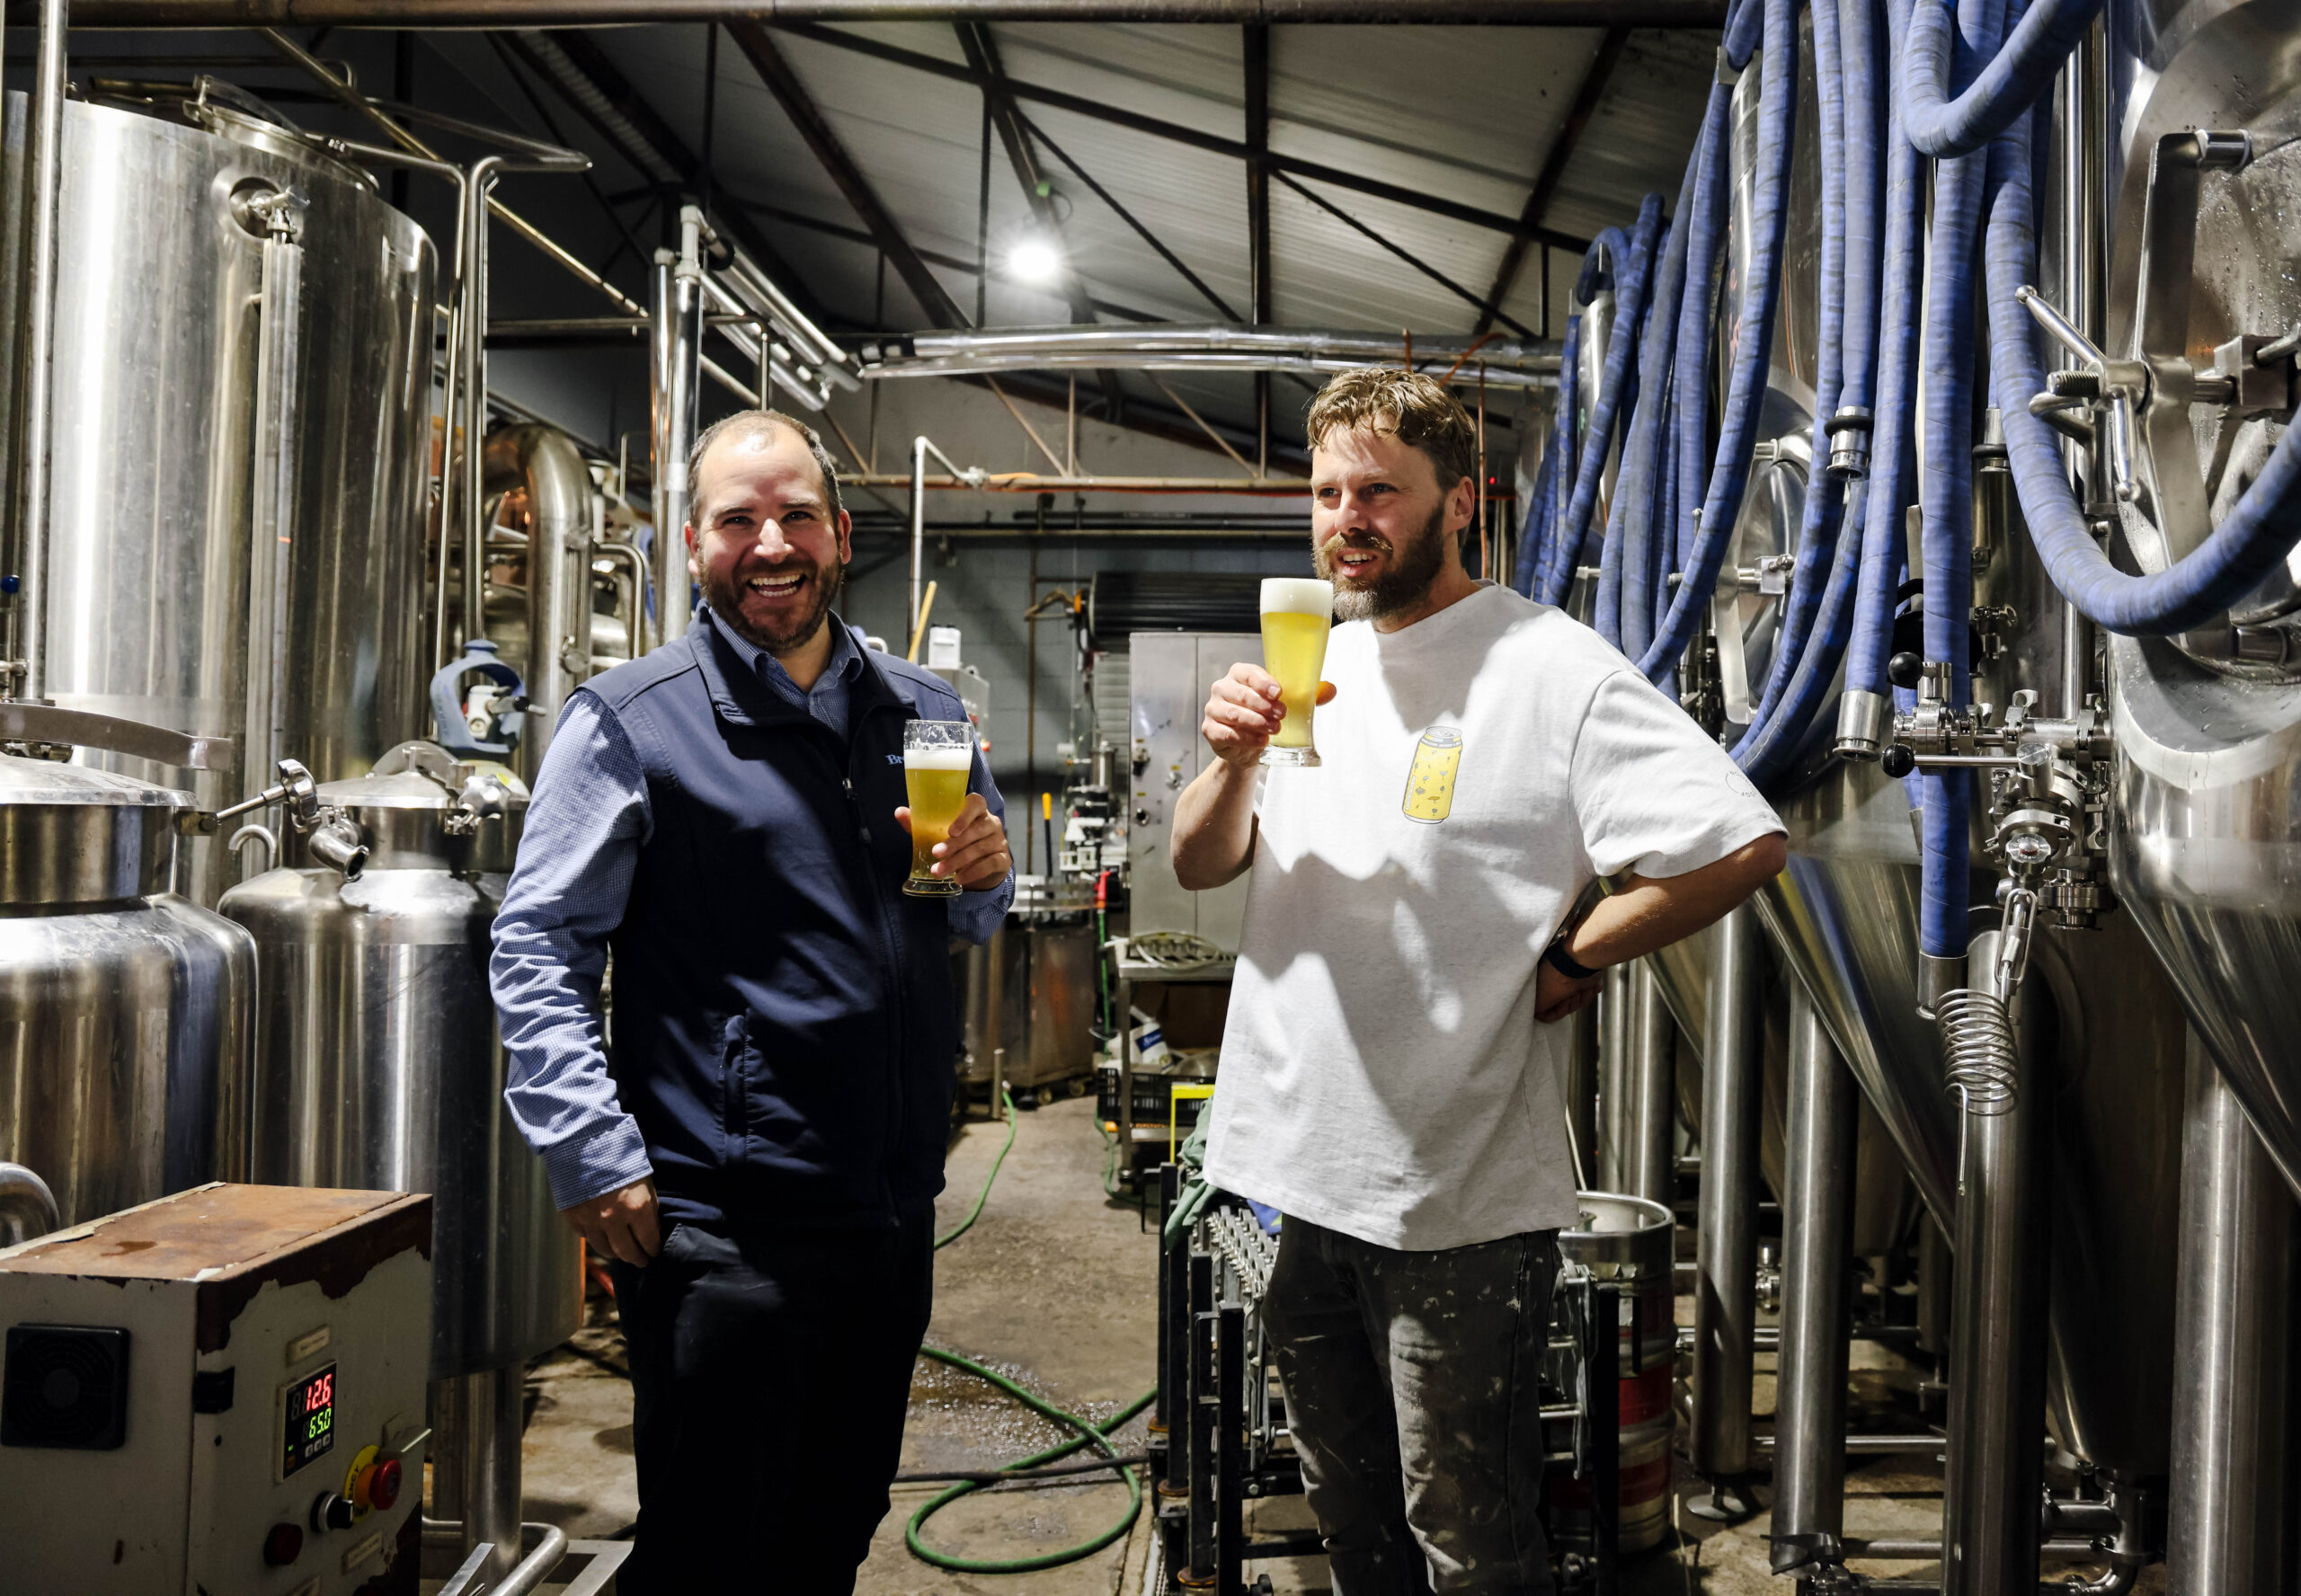
One of our clients, Noodledoof Brewery & Distillery, an independent brewery and distillery based in Koroit, is a good example of what this looks like in practice.
Like a lot of hospitality and production businesses, Noodledoof’s insurance needs aren’t small. There’s cover across the brewery premises, equipment, public liability and more, all renewing at a time that doesn’t always line up neatly with their trading cycle. Paying it all as one upfront amount meant tying up cash that could otherwise go toward staff, supplies, equipment upkeep, or simply riding out quieter months.
We suggested premium funding as an option at renewal, and it’s made a genuine difference to how Noodledoof manages its cash through the year. Alex, an owner of Noodledoof, put it this way:
“When you’re a small, local business, you’ve got to make the most of every strategy available to keep your cash working in your business. Spreading our insurance payments out instead of paying it all in one hit has taken real pressure off. It’s meant we’re not scrambling at renewal time, and that cash can go toward the things that actually grow the brewery. I’m genuinely grateful our broker Corey raised it with us, it’s not something we’d have thought to ask about ourselves.”
Is it right for your business?
Premium funding isn’t a one-size-fits-all answer, and you need to consider the trade-off between the cost of interest and the value of keeping cash flexible in your business. But for many small businesses juggling seasonal cash flow, tight margins, or simply wanting to avoid a lump sum insurance bill, it can be a genuinely useful tool.
If you’re a Warrnambool or South West Victoria business renewing your insurance and the idea of one large lump-sum payment is giving you pause, get in touch with the team at Breakwater to talk through premium funding as part of your renewal conversation.
This article provides information rather than financial product or other advice. The content of this article, including any information contained in it, has been prepared without taking into account your objectives, financial situation or needs. You should consider the appropriateness of the information, taking these matters into account, before you act on any information. In particular, you should review the Product Disclosure Statement (PDS) for any product that the information relates to before acquiring the product.
Information is current as at the date the article is written as specified within it but is subject to change. Breakwater Insurance Brokers make no representation as to the accuracy or completeness of the information. All information is subject to copyright and may not be reproduced without the prior written consent of Breakwater Insurance Brokers.